 By Admin
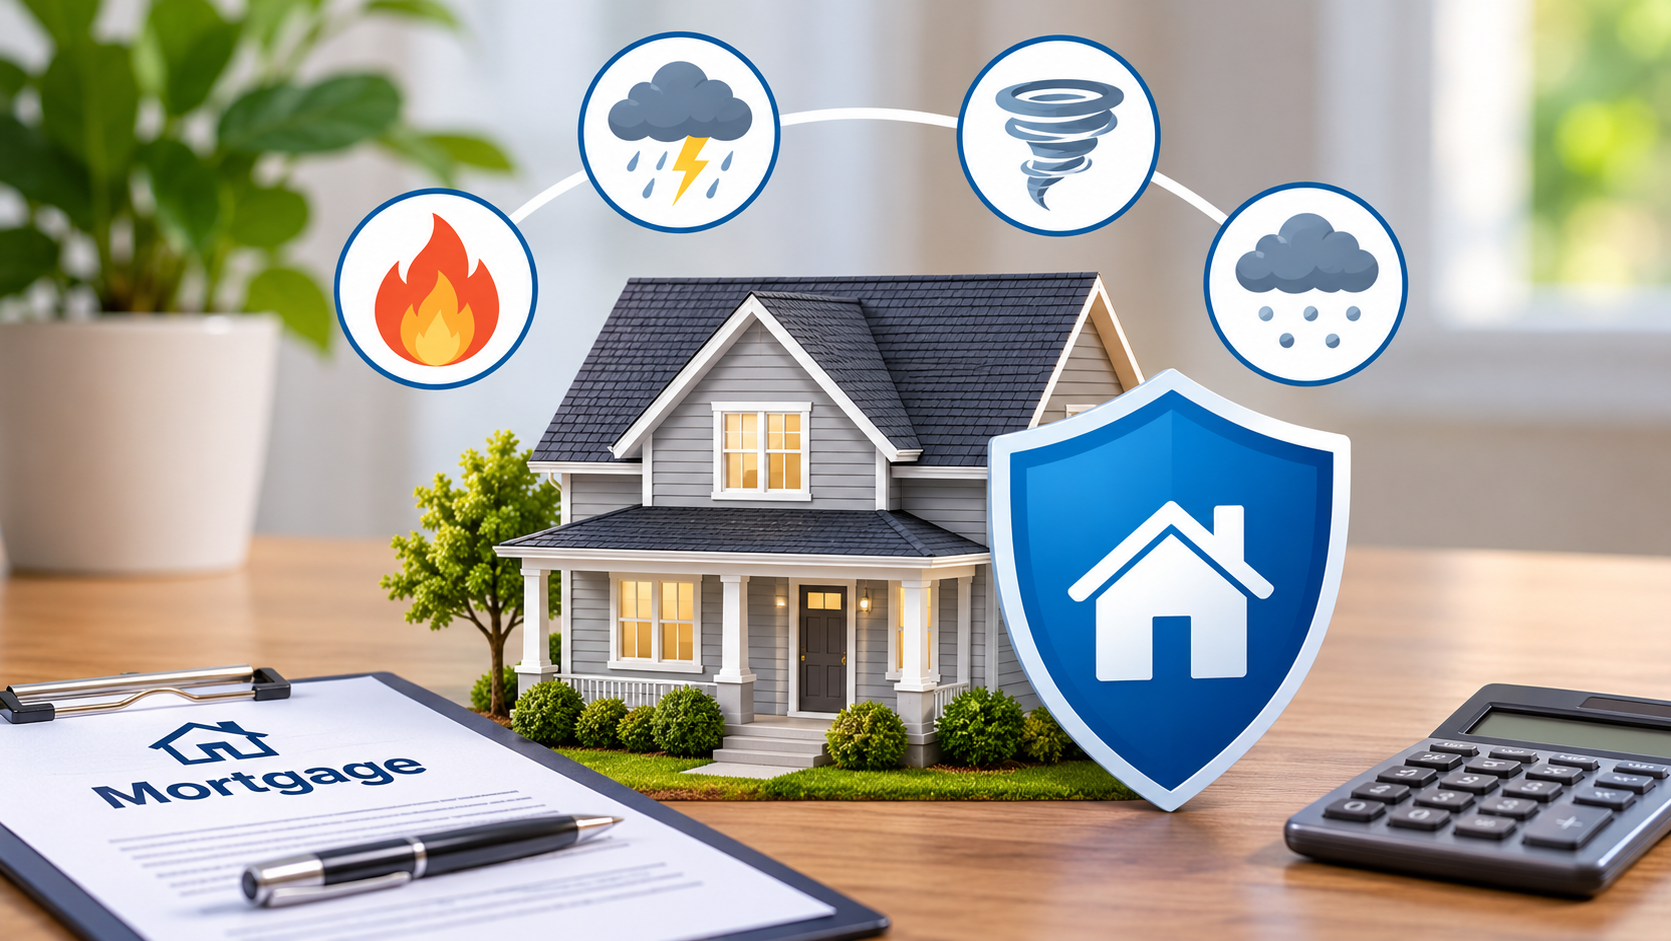
If you’ve noticed an insurance charge on your mortgage statement, you might wonder, what is hazard insurance on my mortgage? Hazard insurance is the part of your homeowners insurance that protects your home’s physical structure against certain unexpected events, such as fires, storms, and other covered damage.
Most mortgage lenders require this protection because your home serves as collateral for the loan. Understanding how hazard insurance works can help you manage expenses and avoid unexpected financial problems. Rocket Mortgage
What Is Hazard Insurance on a Mortgage?
Hazard insurance provides financial protection when your home’s structure suffers damage from an event covered by your policy.
For example, if a severe storm damages your roof, hazard coverage may help pay for repairs after you meet your deductible.
Hazard insurance is generally included in a standard homeowners insurance policy rather than purchased separately.
Mortgage companies often use the term hazard insurance when referring specifically to dwelling protection. farmers.com
Why Do Mortgage Lenders Require Hazard Insurance?
Mortgage lenders require hazard insurance to protect their financial interest in your property.
If your house is severely damaged or destroyed, its value as collateral may decrease.
Insurance helps provide money for rebuilding or repairing the property following covered losses.
Most lenders require borrowers to maintain acceptable coverage throughout the mortgage term.
What Does Hazard Insurance Cover?
Hazard insurance typically protects against several types of property damage.
- Fire and smoke: Damage caused by covered fires.
- Windstorms: Damage from strong winds and certain storms.
- Hail: Roof and exterior damage from hailstones.
- Lightning: Damage resulting from lightning strikes.
- Vandalism: Certain intentional damage caused by others.
- Falling objects: Damage caused by covered events involving falling objects.
Actual coverage depends on your insurance policy, location, and exclusions. NAIC
What Does Hazard Insurance Not Cover?
Standard hazard insurance generally excludes flooding, earthquakes, ordinary wear and tear, and damage resulting from poor maintenance.
Flood and earthquake protection may require separate policies or additional coverage.
Hazard coverage also differs from the personal belongings and liability protections found elsewhere in a homeowners policy.
Is Hazard Insurance the Same as Homeowners Insurance?
Hazard insurance and homeowners insurance are closely related but are not always identical terms.
| Hazard insurance | Homeowners insurance |
|---|---|
| Protects the home’s physical structure | Provides broader protection |
| Covers specified property hazards | May cover belongings and liability |
| Required by most mortgage lenders | Usually satisfies lender requirements |
| Usually part of homeowners coverage | Complete insurance policy |
National Association of REALTORS®
How Much Does Hazard Insurance Cost?
Hazard insurance costs depend on your home’s location, rebuilding value, construction materials, coverage limits, and deductible.
Properties in areas with greater wildfire, storm, or other environmental risks may have higher premiums.
Because hazard coverage is normally included within homeowners insurance, you may not receive a separate hazard insurance bill.
Comparing quotes from multiple insurers can help identify suitable coverage at a competitive price.
Is Hazard Insurance Included in My Mortgage Payment?
Many homeowners pay hazard insurance through a mortgage escrow account.
Your lender collects a portion of the annual insurance premium with each monthly mortgage payment.
When the insurance bill becomes due, the mortgage servicer pays it using the money in your escrow account.
If insurance premiums increase, your monthly mortgage payment may also rise. Consumer Financial Protection Bureau
Can I Remove Hazard Insurance From My Mortgage?
Most mortgage lenders require hazard insurance while the loan remains outstanding.
Canceling coverage without obtaining a replacement policy can create serious financial consequences.
Your lender may purchase force-placed insurance and charge you for it. This coverage is often more expensive and may provide less protection for you.
Even after paying off your mortgage, maintaining homeowners insurance remains a sensible way to protect your property.
How to Find Hazard Insurance on Your Mortgage Statement
Review your monthly mortgage statement or annual escrow analysis.
Look for descriptions such as hazard insurance, homeowners insurance, or insurance escrow.
You can also contact your mortgage servicer to verify your coverage, premium payments, and insurance requirements.
Understanding what is hazard insurance on my mortgage helps you recognize why this coverage matters and how it protects one of your most valuable financial assets.